Motor
What a total-loss valuation actually means
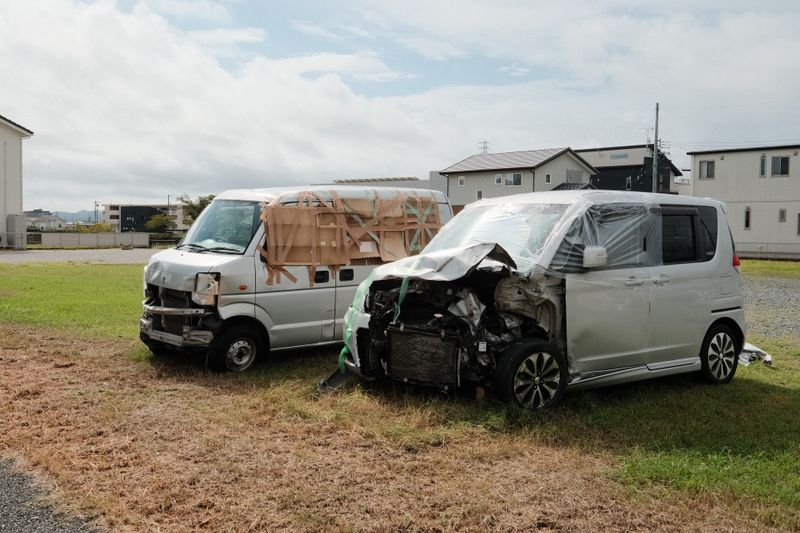
When an insurer writes off a vehicle it pays market value, and market value is a specific figure you can contest.
Treat the sections below as a sequence. With total loss valuations, getting the early decisions right makes the later ones much easier.
Before you start
- Market value means the cost of a comparable replacement, not what you paid or what you owe.
- A first offer is an opening position and is frequently below comparable listings.
- Evidence of actual advertised prices is the most effective way to move it.
Market value is defined narrowly
Policies generally promise market value: what it would cost to buy a comparable vehicle of the same age, mileage and condition. That is not the price you paid, not the outstanding finance, and not the replacement cost of a newer model.
Understanding this in advance removes most of the frustration, because the insurer is applying the contract rather than being difficult. A minority of policies work on a different basis altogether, with new-for-old replacement within a stated period from first registration, or an agreed value fixed at inception for classic and modified vehicles, and for an unusual car an agreed-value policy avoids the entire argument because the figure was settled before the loss.
Where the first figure comes from
Insurers typically use trade valuation guides, sometimes averaged, adjusted for mileage and condition. Those guides lag the market, particularly when used prices are moving quickly, which is why first offers can look low. The offer is a starting position and is negotiable with evidence.
The gap is structural rather than an error, since those guides are built largely from trade and auction transactions while you will be replacing the car at retail, and it is the retail figure that a comparable replacement actually costs.
Evidence that actually works
Screenshots of currently advertised vehicles of the same model, year, mileage and specification, from dealers rather than private sellers. Service history, recent major work, new tyres and desirable options all support an adjustment. Vague assertions that the car was in excellent condition do not; documented comparables do.
The useful part is this: comparability is what the insurer will attack, so the advertisements need to match on variant and transmission, sit within a reasonable mileage band, and carry a captured date and source — and a spread of several is more persuasive than the single highest one you could find.
Finance and gap cover
If outstanding finance exceeds market value, the shortfall is yours unless you hold gap insurance. This is common in the early years of a finance agreement and is the main reason gap products exist. Gap cover is frequently sold at the dealership at a substantial markup and is usually cheaper bought separately.
Gap products also differ in what they restore, since a finance shortfall policy only clears the outstanding agreement while a return-to-invoice or replacement policy aims at the original purchase price or a new equivalent, and buying the cheaper type without registering which is which is the usual mistake.
Keeping the vehicle
You can often retain a written-off vehicle, with the salvage value deducted from the settlement. Whether it can legally return to the road depends on the write-off category in your jurisdiction. A retained write-off carries a permanent marker that affects future value and insurability.
Retention is not always on offer either, since a vehicle on finance or lease generally belongs to the lender until the agreement ends and the settlement goes to them first, and the salvage deduction is based on what the wreck would fetch at auction rather than on what it is worth to you.
The clock works against you once the offer lands
A courtesy or replacement vehicle usually stops at the point the total loss is agreed rather than when you have found something to replace it with, so the real cost of a long negotiation is transport you fund yourself. Recovery and storage charges can accrue at the salvage yard while a valuation is argued over, and in some settlements they are deducted from what you eventually receive.
In practice, acceptance of a settlement is generally treated as final, so where you intend to keep arguing it is worth asking explicitly whether the undisputed portion can be paid on account while the valuation remains in dispute, rather than banking a full and final payment and objecting afterwards. If the insurer will not move, the complaints process and then the relevant independent scheme are the routes available in most jurisdictions, and an independent engineer's report is the kind of evidence those schemes tend to weigh.
The takeaway
Collect comparable advertisements before you respond to the first offer.
The version you keep doing is the version that works.
Questions readers ask
Can I challenge a write-off valuation?
Yes. Provide dated advertisements for genuinely comparable vehicles and ask the insurer to reconsider in writing. If it stands, use the complaints process and then the ombudsman.
Does a write-off affect my premium?
It is recorded as a claim and generally affects renewal pricing and the no-claims discount, whether or not you were at fault.